Why Do Banks Pass On RBA Rate Rises? What If One Didn't?
Australian banks are not legally required to pass every RBA interest rate increase on to mortgage customers. They set their own lending rates, taking into account funding costs, competition, risk and profitability. A bank could absorb some or all of an increase, although doing so would reduce its interest margin unless offset elsewhere. That raises a fascinating business question: could a bank earn more over time by sacrificing some short-term profit to win customer trust, loyalty and market share?
The Reserve Bank raises interest rates. The banks pass them on. Mortgage holders pay more.
Same story. Every time.
Who says the banks have to pass on the increase?
They don’t.
It’s a commercial decision.
Banks have funding costs to manage, shareholders to satisfy and profits to protect. Fair enough.
But imagine if one of Australia’s major banks decided to do something different.
The most powerful campaign they never ran.
Imagine the Commonwealth Bank announcing:
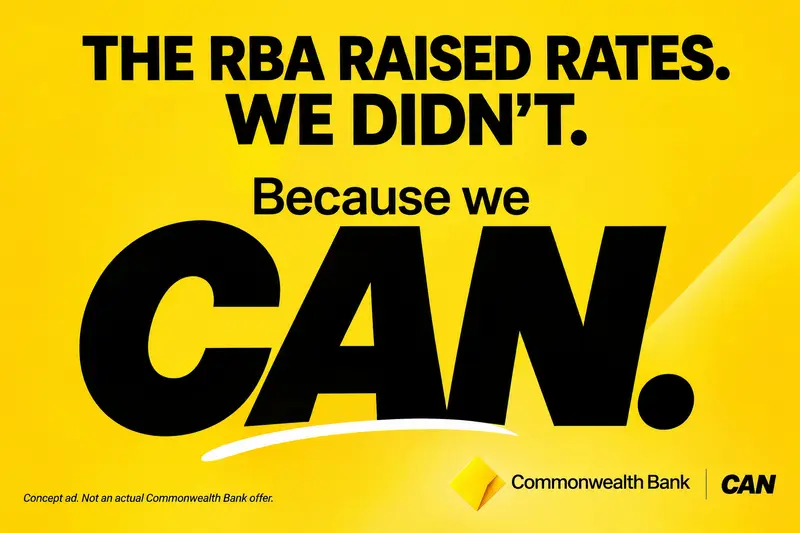
Think about the reaction.
The headlines. The publicity. The conversations around dinner tables across Australia.
Millions of mortgage holders would suddenly have a reason to look at CBA differently.
And plenty might start looking at their own bank differently, too.
Banks spend enormous amounts of money trying to convince Australians they’re different.
Then interest rates rise, and they largely behave the same way.
What would happen if one broke ranks?
Could a bank make more money by making less?
CBA reported $10.87 billion in cash net profit after tax for FY2026.
That’s approximately $29.8 million a day.
Of course, absorbing an interest rate increase would cost money. Banks don’t get their funding for free.
And the economics matter.
If a bank absorbed a 0.25 percentage-point increase across a $500 billion mortgage portfolio, the potential annual revenue impact would be around $1.25 billion, before allowing for changes in funding costs, customer behaviour and other factors.
That’s serious money.
But so is the lifetime value of a customer.
A mortgage relationship can last decades. And banks want more than your mortgage.
Savings accounts. Credit cards. Business banking. Insurance.
A customer who trusts their bank is potentially worth far more than the interest earned on one home loan.
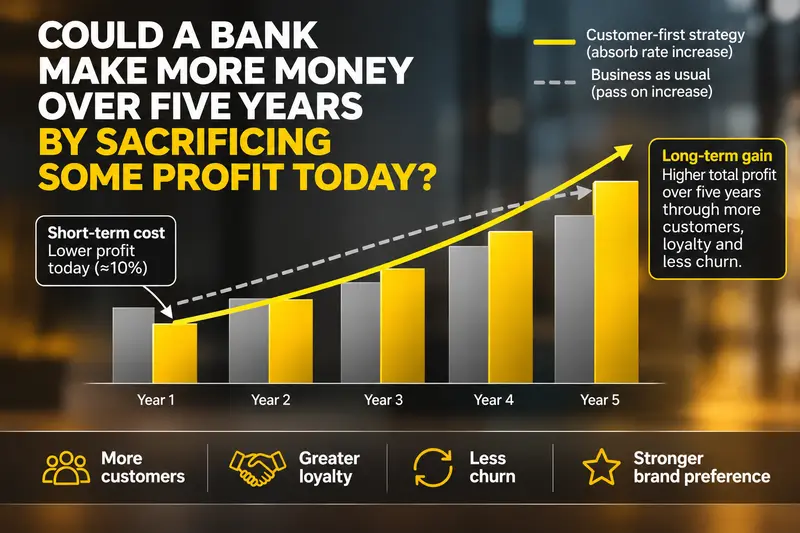
What if absorbing half the increase attracted thousands of new customers?
What if it reduced customer churn?
What if it encouraged existing customers to bring more of their banking across?
Could sacrificing profit today create greater profits over five years?
That’s a business case worth exploring.
What is customer trust actually worth?
Every major bank talks about putting customers first.
It’s in their advertising. Their websites. Their corporate values.
And Australians have heard it all before.
Imagine the impact of a bank demonstrating that commitment when customers were feeling the financial pressure.
It wouldn’t even need to absorb the entire increase.
Half the increase. A three-month freeze. A meaningful reward for long-standing customers.
Any of those decisions could give people a reason to reconsider what they think about their bank.
And when you change what people think about you, you change how they behave towards you.
That’s branding.
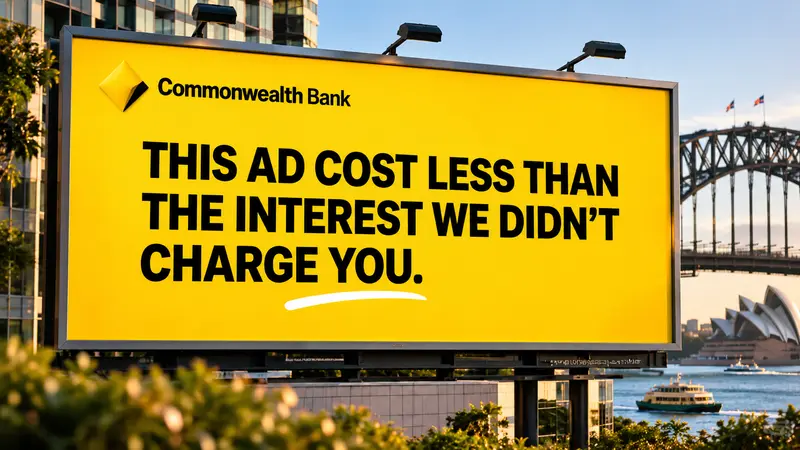
Branding is what you do.
A brand is built through the decisions a business makes and the experiences those decisions create.
Advertising can communicate a promise.
Business behaviour determines whether people believe it.
A bank that absorbed an interest rate increase would be making a very public statement about its priorities.
Would the numbers stack up?
That’s the question its finance team would need to answer.
But imagine the brand value if they did.
The most powerful brand statement a bank could make might have nothing to do with its advertising.
It could be the interest rate it chooses not to charge.